Erik Walbot · The Payoff Pro
Pay off your home. Build your freedom.
A traditional mortgage keeps your paycheck sitting idle while your balance barely moves — for 30 years. The All In One Loan™ works the other way: every deposit lands on your principal, and interest is recalculated daily on what's actually left. Homeowners who use it measure the finish line in years, not decades.
Why it works
Three things a regular mortgage can't do
Pay less interest
Interest on a traditional loan runs off a schedule set at closing. Here it's recalculated daily on what you actually owe — and every deposit drops that balance the day it lands. Less balance, less interest, every single day.
Own your home sooner
When the balance falls faster, the finish line moves toward you. Many households see a payoff window of 5–10 years instead of 30. Run the simulator below and see what your numbers say.
Keep access to your equity
Pay down a regular mortgage and that money is locked away until you sell or refinance. The All In One stays open: your equity remains there to draw on across the loan's full 30 years — without a new loan or a new application.
“The loan my wife and I have on our own house. We could have picked any mortgage in the country. We picked this one — for the same three reasons on this page: less interest, a faster finish line, and our equity still there when we need it. I don't sell anything I wouldn't sign myself.”
The mechanism
How the All In One Loan™ works
It's a first-lien HELOC with a built-in sweep checking account. There's no new habit to learn and no extra payments to make — your normal income does the work.
Your paycheck deposits into the loan's built-in checking account — and lands directly on your mortgage principal the day it arrives.
Interest is charged on the lower balance, every day. Your rate is the 30-day average SOFR plus a margin that's fixed for the full 30 years — and it falls automatically when SOFR falls. No refinance needed.
Spend as usual from the same account. Every dollar works against your balance until the moment you spend it — and the line stays open for all 30 years.
Run the comparison
See your two paths, side by side
This is CMG's official simulator: put in your loan, your income and what you spend, and watch the traditional path and the All In One path race each other.
Run the full simulator
The complete All In One simulator runs on CMG's site — same tool Erik walks his clients through, opens in a new tab:
Simulator provided by CMG Home Loans. All In One Loan™ and the All In One Loan™ logo are trademarks of CMG Home Loans, NMLS #1820. Results are estimates from CMG's simulator, not a loan offer or commitment to lend. Loan services: Erik Walbot, Mortgage Strategist, EPiQ Lending, NMLS #2018707 (company NMLS #1936984). This page is educational only.
Watch & learn
The Payoff Pro video library
Erik explains the strategy on YouTube — the mechanics, the traps in a “low” rate, and the roadmap from first call to closing. Tap any video to play it right here.
Swipe or scroll for more · Watch the full library on YouTube →
The 60-second payoff check
How much is your current path costing you?
What's left on your mortgage?
Straightforward, on purpose
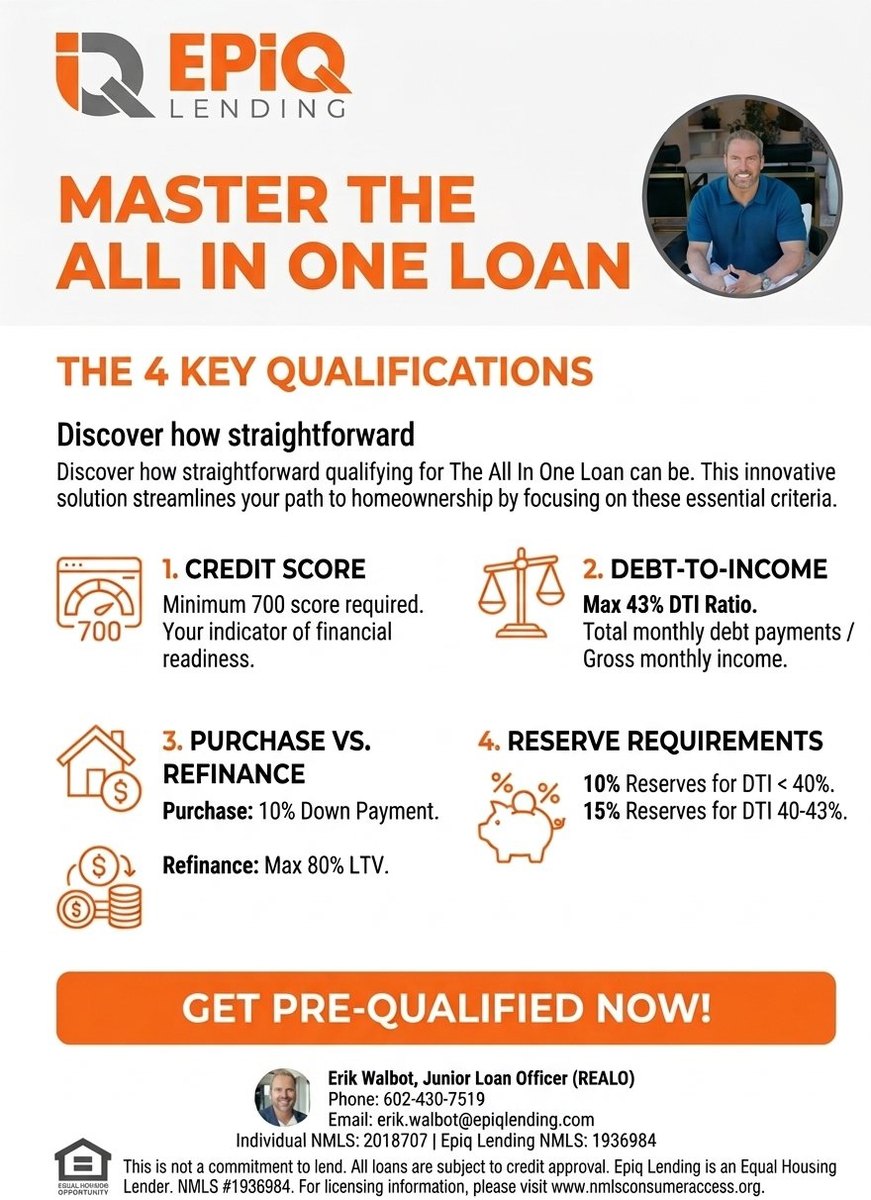
The 4 key qualifications
Minimum 700
Your indicator of financial readiness. 700 or higher opens the door.
Max 43% DTI
Total monthly debt payments divided by gross monthly income.
10% down · 80% LTV
Purchase: 10% down payment. Refinance: maximum 80% loan-to-value.
10% – 15% on hand
10% reserves if your DTI is under 40%; 15% if it's 40–43%.
Quick questions
Before you ask
Can I still get to my equity if something comes up?
Yes — that's the point of the design. The line stays open across the loan's full 30 years, so the equity you pay down is still yours to draw on when life happens. No new loan, no new application.
Do my paychecks have to be perfectly steady?
No. Every deposit sweeps against your principal the day it lands, whenever it lands. Irregular income changes the pace, not how it works — and Erik can model lumpy income in your scenario so you see your real path.
Do I have to change how I bank?
The loan comes with its own built-in checking account — that's the sweep. The income you route through it is what works against your balance until you spend it. You can keep your other accounts; the deposits doing the work just need to flow through this one.
What does it take to qualify?
Generally: a 700+ credit score, a debt-to-income ratio up to 43%, 10% down on a purchase (or up to 80% loan-to-value on a refinance), plus reserves. Your exact picture decides it — that's a two-minute conversation, not a guess.
Want Erik to run your exact scenario?
The simulator is the model. Erik is the strategist. Send the 60-second check above, or just call — he'll run your real numbers and tell you plainly whether this fits, including when it doesn't.
Buying or selling a home instead?
Erik is a Scottsdale realtor first — 25 years, 500+ homes sold. Real estate lives at The Walbot Group.
It's your journey — let us be your guide
Run your exact scenario with Erik
Two minutes on the phone beats two hours of guessing. Erik will model your numbers and give you a straight answer — including if the All In One isn't your move.
Erik Walbot · Mortgage Strategist · AIO Specialist · EPiQ Lending
7975 N Hayden Road, Ste A101, Scottsdale, AZ 85258